
How should you pay yourself when starting a company

How you choose to pay yourself as a company director can have a significant impact on both your personal tax position and your business finances. Whether you’re starting a new company or reviewing an existing remuneration strategy, finding the right balance between salary and dividends is key to maximising tax efficiency while remaining compliant with HMRC requirements.
In this article, Mark Rubinson explores the importance of structuring remuneration in a way that’s tax-efficient, commercially practical and aligned with your long-term goals.
For directors and shareholders of small and medium-sized enterprises (SMEs), structuring your remuneration is one of the most important financial decisions you’ll make.
Most directors aim to minimise their tax liabilities. The key challenge is to find the right balance between salary and dividends while complying with legal requirements and maintaining good cash flow. If the balance isn’t quite right, you may be paying too much tax.
This guide runs through the interaction between salary and dividends. We include examples that illustrate whether it’s better for directors and shareholders to take salary or dividends.
What is directors’ remuneration?
Directors’ remuneration refers to the financial compensation a director receives from his/her business. For owner-managed companies (usually SMEs), this typically consists of a salary topped up by dividends which are paid out of company profits and tend to be taxed at a lower rate than salary as they don’t attract National Insurance making them an attractive option for director-shareholders.
What are directors’ drawings?
Until recently, it was common practice for SME directors to take a small salary and rely heavily on dividends to be tax efficient. However, changes in income tax and national insurance rates in recent years means the mix should possibly be re-assessed. This could save tax and increase net drawings for the director/shareholder.
Best practices for structuring remuneration
For most SME directors, the optimal approach is to take a reasonable salary supplemented with dividends.
Here are the main factors to consider:
- Directors typically take a salary that ensures they meet minimum National Insurance thresholds while also benefitting from pension contributions. A salary also allows directors to make full use of their personal tax allowance
- Dividends remain an attractive way for SME directors to extract profits, as they are taxed at lower rates than salary. However, dividends can only be taken if the company has sufficient retained profits, so careful planning is necessary
This approach is primarily about “crunching the numbers” to identify the most tax-efficient strategy.
The examples below show that structuring income with a minimal salary and higher dividends significantly reduces tax liabilities, particularly PAYE and National Insurance. By taking advantage of lower dividend tax rates, individuals can increase their net take-home pay. The tax savings grow with higher income levels, demonstrating that a strategic balance between salary and dividends leads to greater tax efficiency and financial benefits.
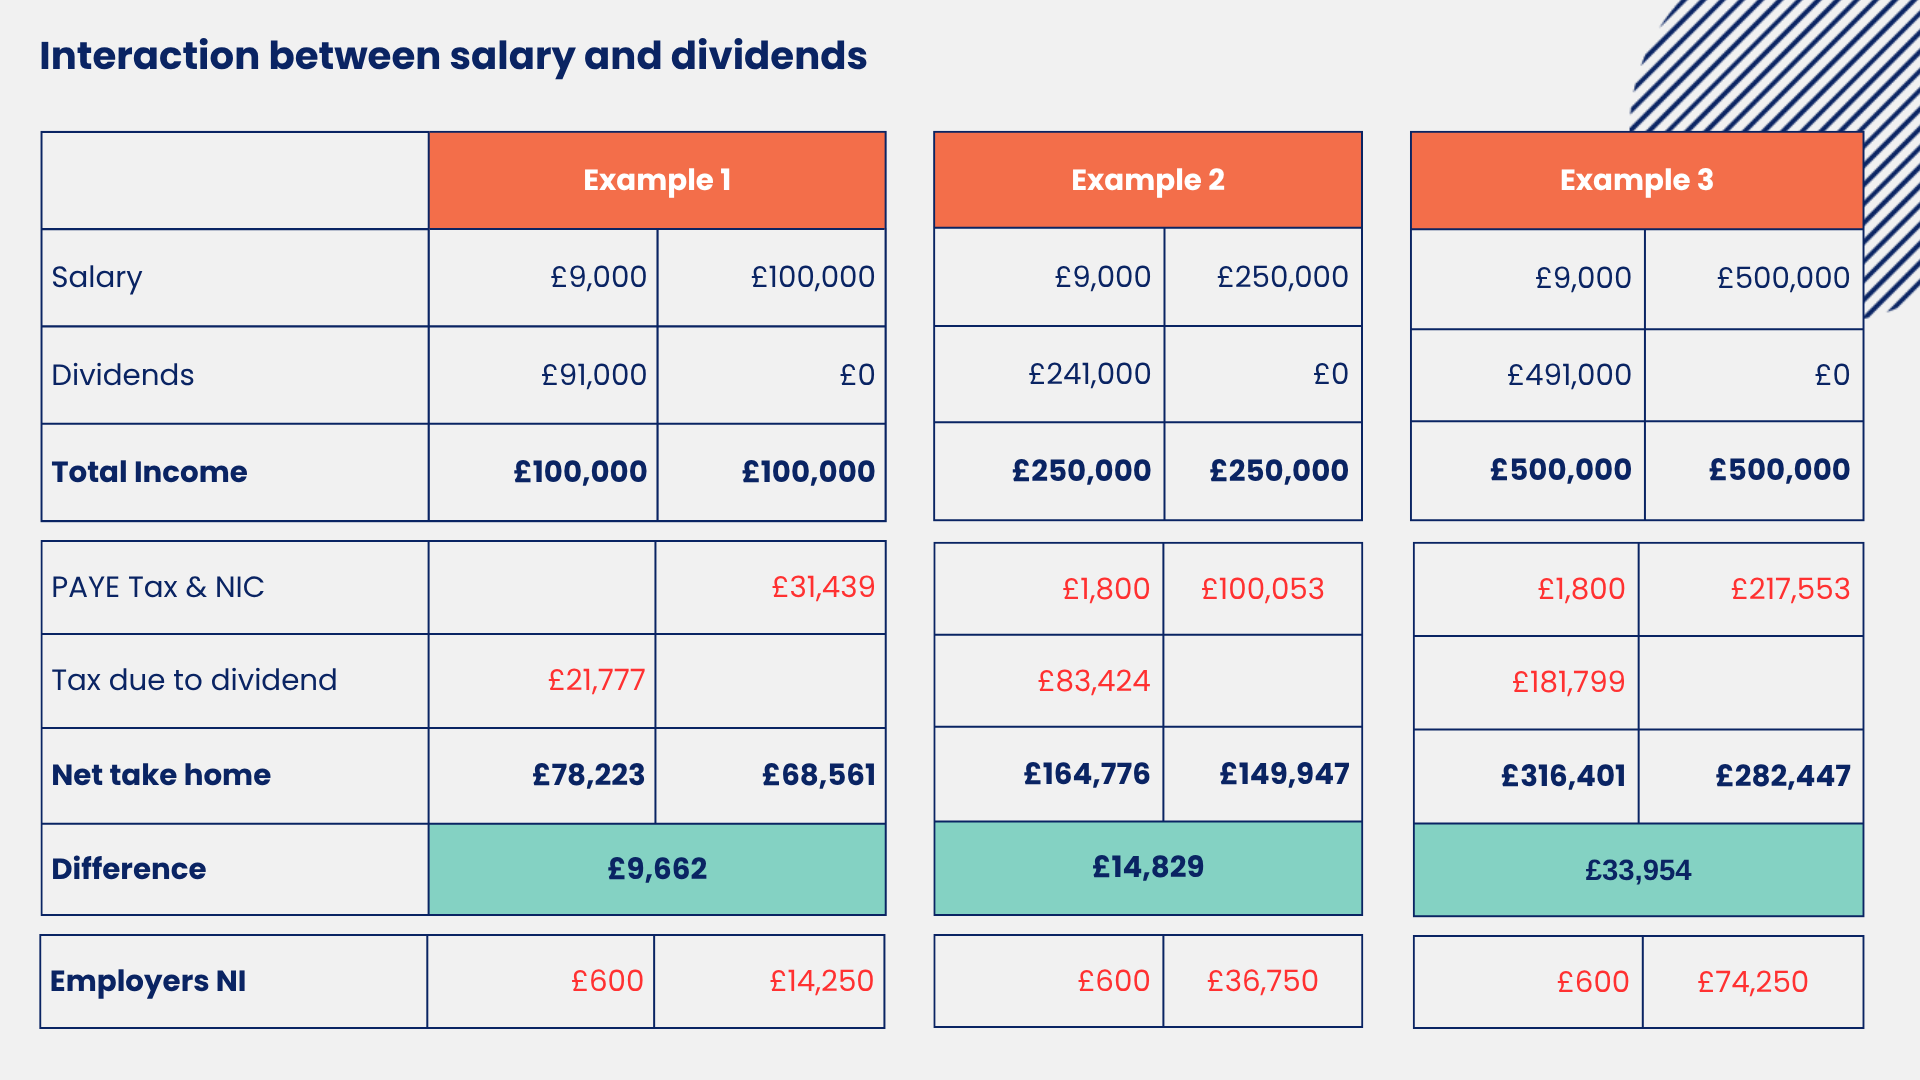
It’s crucial to continually re-assess the balance between salary and dividends to ensure there’s not an overpayment of tax and national insurance. It’s also important to understand the interaction with Corporation Tax.
Legal and statutory requirements
Even though SMEs don’t face the same reporting pressures as large companies, compliance with statutory requirements is still necessary. Directors of SMEs also have fiduciary duties to act in the best interests of the company. This means ensuring that any remuneration decisions are in line with the company’s financial stability and cash flow. Taking excessive remuneration could be viewed as acting against the company’s interests.
Key considerations for SMEs
When deciding how to structure directors’ drawings, here are the key considerations for SMEs and owner-managed businesses:
- Tax planning is crucial when structuring remuneration
- In SMEs, the directors and shareholders are often the same people. This means that decisions about remuneration affect not just your personal finances but also the company’s ability to reinvest profits and grow
For many SMEs, consulting a specialist who understands the nuances of tax efficiency can help ensure that all factors are managed optimally without risking compliance or profitability.
Common questions from SME directors
How should directors take money out of their companies?
The most tax-efficient method is usually a combination of salary and dividends. The salary ensures you meet National Insurance and pension thresholds, while dividends provide an additional income stream and can be more efficient with regard to tax and national insurance. However, dividends can only be paid out of retained profits, so careful financial planning is required.
What are the tax implications of salary versus dividends?
Salary is subject to income tax and National Insurance contributions, while dividends are usually taxed at a lower rate. Structuring remuneration to balance both can reduce your personal tax liability while ensuring the company maintains sufficient profits to reinvest in the business.
What are the reporting obligations for directors’ remuneration?
SMEs are required to comply with basic statutory reporting under the Companies Act, including disclosing directors’ remuneration in the financial statements. Ensuring transparency in reporting can help avoid legal issues and maintain shareholder trust.
Why Gravita?
For SMEs and owner-managed businesses, directors’ remuneration is about more than just choosing a salary. It’s about finding the right balance between salary and dividends to achieve tax efficiency, stay compliant with legal obligations, and protect the company’s financial health. Regularly reviewing your remuneration strategy ensures that both you and your business are benefiting from the best possible financial outcomes.
At Gravita, we specialise in helping SMEs optimise their directors’ remuneration strategy. Our expert team can help you find the most tax-efficient structure, ensuring that you’re compliant with all relevant regulations and aligned with your business’s goals. Contact Partner, Mark Rubinson to get advice on ensuring your mix of salary and dividend is tax efficient.
Read our article on Directors’ Remuneration for AIM-listed companies
Similar Insights
UK GAAP changes: What your business needs to know
Pre-revenue accounting: Getting your start-up’s finances right from day one
How AI is changing accountancy
Sign up to Gravita's latest updates and newsletters
Stay up-to-date with our event invites, latest news and updates, straight from Gravita's experts.